Industry risk analysis identifies and quantifies the sector-level threats that can move an entire industry, so risk managers can prioritize responses and protect financial outcomes. The output is a ranked set of exposures, a rough dollar estimate of what each could cost, and a mitigation plan tied to that ranking. Practitioners build it using frameworks like COSO, quantitative signals like sector beta, and granular sector data from providers such as Bizminer.
TL;DR:
- Industry risk analysis measures sector-wide threats, focusing on macro trends and correlations that can impact all companies in the sector simultaneously.
- Sector beta, input price exposure, and earnings-at-risk models are key quantitative tools used to gauge macro sensitivity and operational impact.
- Risks tend to cluster around factors like customer concentration and cyclical demand, requiring aggregation and cluster-based responses rather than isolated fixes.
- A structured process involving scope definition, risk identification, scoring, and regular monitoring improves accuracy and relevance over time.
- Using granular, credible benchmarks such as Bizminer reports ensures risk models reflect real sector conditions and withstand regulatory or legal scrutiny.
Table of Contents
- What Does Industry Risk Analysis Actually Cover?
- Key Industry Risk Factors: A Checklist for Any Sector
- Which Methods and Metrics Actually Measure Sector Risk?
- How Do You Run an Industry Risk Analysis Step by Step?
- Building Scenario Analysis and Stress Tests That Hold Up
- Turning Risk Scores Into Board-Ready Recommendations
- A Compact Case Study: Applying the Framework to Regional Trucking
- Where Most Industry Risk Analysis Efforts Go Wrong
- Put Industry Benchmarks Behind Every Risk Score You Report
- Further Reading and Primary Sources
- Sources
What Does Industry Risk Analysis Actually Cover?
Industry risk analysis looks at the forces acting on an entire sector, not the balance sheet of one company inside it. A company-level review asks whether a specific borrower or portfolio holding can survive a downturn. An industry-level review asks whether the downturn is coming at all, and how hard it will hit everyone in that sector at once. Both matter, but they answer different questions, and confusing them is one of the more common mistakes risk teams make.
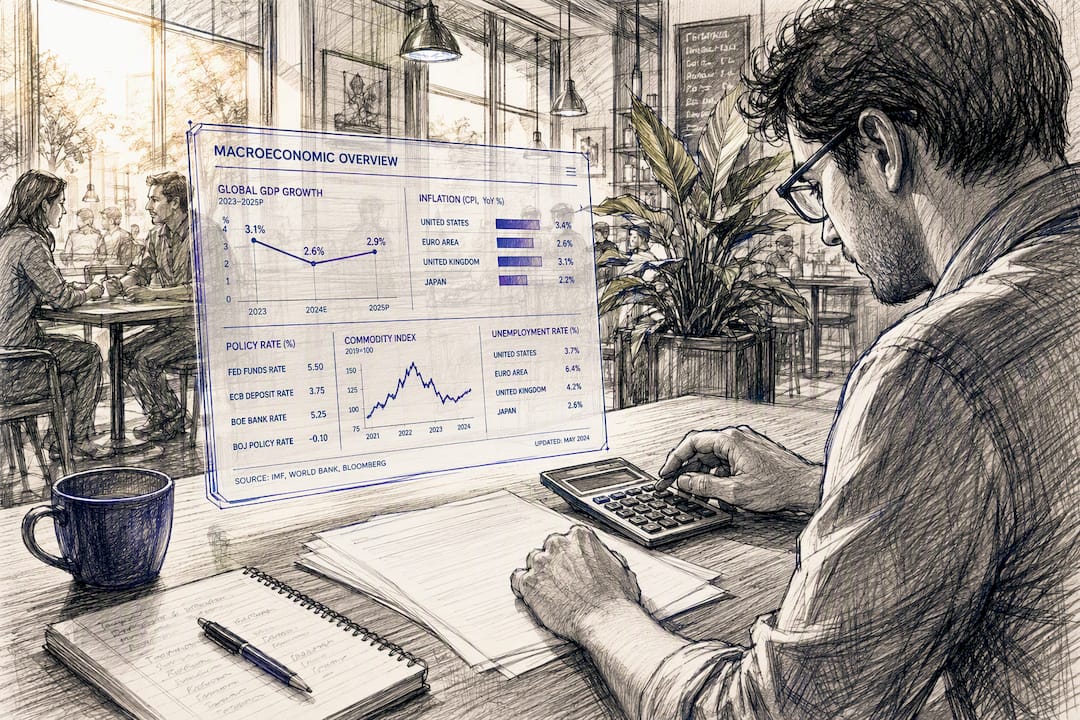
The distinction shows up constantly in underwriting. A loan officer evaluating a restaurant group needs company financials, sure, but the real predictive power often comes from knowing that full-service dining margins compress fastest when discretionary spending drops. That’s an industry fact, not a company fact, and it changes the loan terms before a single covenant is written.
Strategy teams use industry risk analysis differently. Before entering a new market or divesting a business line, leadership needs to know whether the sector itself is structurally sound or riding a temporary tailwind. M&A teams lean on it even harder: acquiring a company in a sector facing regulatory tightening or margin erosion changes the entire valuation model, regardless of how clean the target’s books look.
A few concrete use cases show the range:
- Underwriting and credit decisions: lenders adjust loan pricing and covenants based on sector volatility, not just borrower history.
- Corporate strategy: leadership teams decide whether to expand, hold, or exit a market segment based on structural sector trends.
- M&A due diligence: acquirers price in sector-level risk that no amount of target-company diligence will reveal.
- Supplier strategy: procurement teams diversify vendors when a supplying industry shows concentration or geopolitical exposure.
Sector shocks propagate through financial statements in predictable but often underestimated ways. A commodity price spike doesn’t just squeeze margins at the companies that buy the commodity. It ripples into their customers’ pricing power, their lenders’ risk appetite, and eventually into unrelated sectors that share suppliers or labor pools. Treating an industry as an isolated silo is how risk managers get blindsided by the second-order effects nobody modeled.
Key Industry Risk Factors: A Checklist for Any Sector
Every credible sector review runs through a consistent set of factors, whether you’re evaluating auto parts manufacturing or regional banking. The Pomegra industry analysis checklist frames this as market structure, growth, competitive dynamics, profitability, and disruption or regulatory risk, revisited at least once a year or whenever conditions shift materially. That cadence matters. A checklist built in a stable rate environment goes stale fast once the Fed moves.
Here’s a working sequence that covers the ground without missing the interactions between factors:
- Market demand and cyclicality. Is demand tied to consumer discretionary spending, business capital cycles, or something more stable like utilities? Cyclical sectors need wider risk buffers.
- Input and supplier concentration. How many suppliers exist for critical inputs, and how exposed is the sector to a single commodity or geographic source?
- Competitive dynamics and substitution risk. Are new entrants easy, and is there a cheaper or better substitute product waiting in the wings?
- Regulatory and political risk. Does the sector depend on licensing, subsidies, tariffs, or rules that could change with a single legislative session?
- Technology and disruption risk. Is the sector’s core business model vulnerable to automation, platform shifts, or a faster-moving adjacent industry?
- Customer concentration. Does revenue depend on a handful of large buyers who could walk away or renegotiate terms?
- Life-cycle stage and exit barriers. Is the sector growing, mature, or declining, and how costly is it for weak players to exit rather than drag down pricing for everyone?
Financial Edge’s training material on industry risk breaks this down into nine factors including supplier power, customer power, and barriers to entry, which is worth reviewing if you want a more granular framework for credit-focused analysis specifically.
Pro Tip: Weight these factors differently depending on the sector’s maturity stage. A young, high-growth industry cares more about substitution and technology risk; a mature, consolidated industry cares more about customer concentration and exit barriers. Applying the same weighting scheme to both is a fast way to produce a misleading risk score.
Which Methods and Metrics Actually Measure Sector Risk?
Most mature risk functions run a two-stage process: broad qualitative screening first, then quantitative analysis applied only to the risks that survive that first cut. The Deloitte and COSO practical paper on risk assessment recommends exactly this sequencing, and it saves teams from burning analyst hours quantifying risks that never had a real chance of materializing.
Qualitative screening and heat maps come first for a reason. A heat map plots likelihood against impact, using color bands, red for severe and likely, green for minor and unlikely, to give a fast visual read on where attention belongs. This works well in workshop settings where you’re pulling in input from underwriters, sales, and operations who don’t speak in probability distributions but can absolutely tell you which risks keep them up at night.
Sector beta is the quickest quantitative signal available once you’ve narrowed the field. Beta measures how a sector’s returns move relative to the broader market: a beta above 1.0 means the sector amplifies market swings, a beta below 1.0 means it dampens them. Utilities typically run below 1.0 because demand holds steady regardless of the economic cycle. Homebuilders and semiconductor equipment makers often run well above it, since both are exposed to interest rate cycles and capital spending swings that hit harder than the broad market average. Beta is a fast macro-sensitivity check, not a full risk model, and pairing it with sector-specific measures like input-price exposure or customer concentration gives a much better read on operational impact.
Aggregated measures like gross margin at risk or earnings at risk translate the qualitative and beta-level signals into numbers a CFO can act on. These estimate how much of current earnings or margin could evaporate under a defined stress scenario, and they force analysts to be explicit about assumptions instead of hiding behind a red dot on a heat map.
Risk interactions and correlation get missed constantly. A recent academic treatment of risk aggregation makes the point that risks rarely move independently. A supply shock and a demand shock hitting the same quarter compound rather than simply add, and any aggregation method that treats risks as isolated line items will understate the tail scenario.
Some sectors also get scored through structured multi-factor models. CRISIL’s Industry Risk Score methodology aggregates demand-supply balance, input risk, competitive intensity, and financial performance into a single forward-looking score over a three to four year horizon, useful for credit portfolio monitoring, though it needs updating at least annually to stay relevant.
Data requirements scale with the method. Heat maps run on workshop input and judgment. Sector beta needs public market return data. Earnings-at-risk modeling needs granular financial benchmarks, cost structure data, and historical volatility figures, which is exactly the kind of input Bizminer’s industry reports are built to supply.
How Do You Run an Industry Risk Analysis Step by Step?
A repeatable process beats a brilliant one-off analysis every time, because risk conditions change and you’ll be running this again in six months. Here’s a workflow that holds up across sectors.
1. Scope the analysis. Define the industry boundary precisely. “Retail” is too broad to be useful; “specialty apparel retail” or a specific NAICS code gets you somewhere actionable. Bizminer’s NAICS industry search tool is built for exactly this step, letting you pin down the right classification before you pull a single data point.
2. Identify the risks. Pull from multiple sources rather than relying on one analyst’s intuition. Regulatory filings, earnings call transcripts, trade publication coverage, and structured interviews with people inside the sector all surface different risks. UCLA’s guidance on assessing risk recommends combining document review with direct interviews specifically because documents capture what’s already known, while interviews surface what’s changing.
3. Assess each risk against consistent criteria. Score every identified risk on:
- Impact (how much revenue, margin, or capital is exposed)
- Likelihood (probability of occurrence within the planning horizon)
- Vulnerability (how exposed your specific position is, versus the sector broadly)
- Speed of onset (does this risk build over years or hit in a quarter)
4. Prioritize using aggregation, not just individual scores. Plot results on a heat map, but then step back and look for clusters. Three moderate risks that share a root cause, say, interest rate sensitivity, deserve more attention together than any one of them does alone.
5. Select responses. Standard options are avoid, mitigate, transfer (insurance or hedging), or accept. The choice should map to your organization’s risk appetite, not to whichever response feels most comfortable in the moment.
6. Monitor on a fixed cadence. Annual reviews work for stable sectors. Quarterly reviews make more sense for anything moving through regulatory change, rapid technology shifts, or acute macro exposure. Set the cadence at the start, don’t let it drift based on how busy the team is that month.
Building Scenario Analysis and Stress Tests That Hold Up
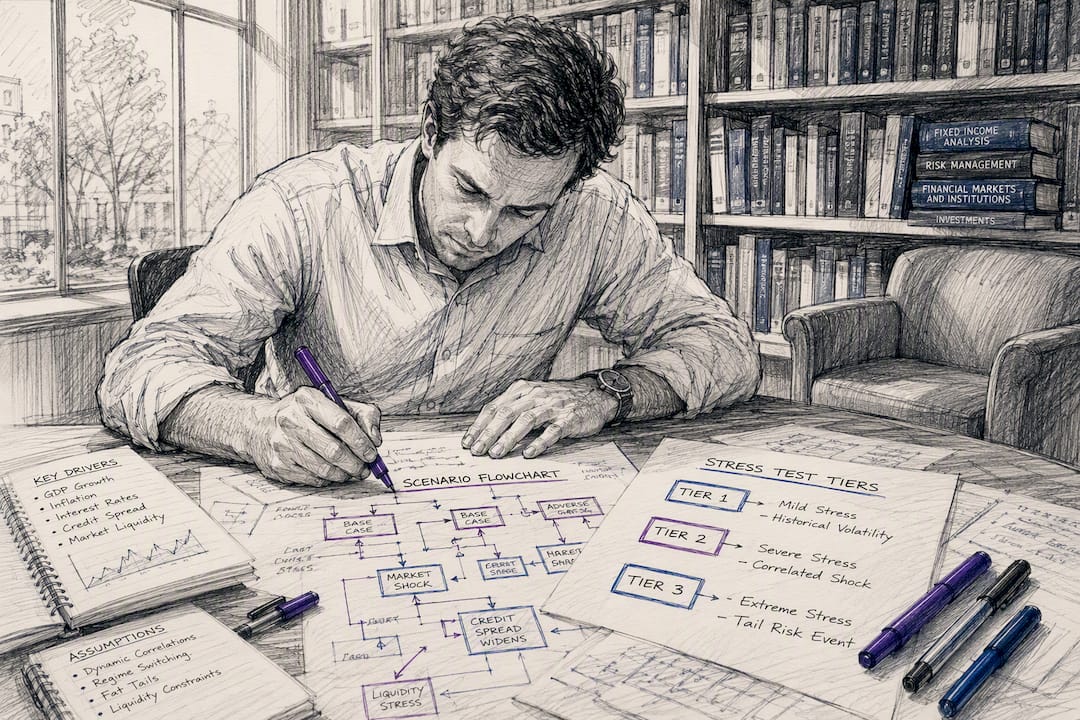
Turning risk factors into scenarios is where industry risk analysis stops being a list and starts being a forecasting tool. GARP’s practical guide to stress testing recommends building at least three tiers: a baseline case reflecting current trends, an adverse case reflecting a plausible downturn, and a severe case reflecting a low-probability, high-impact shock.
Each scenario needs specific, defensible assumptions rather than vague direction. That level of specificity is what lets you translate the scenario into an actual earnings-at-risk or cash-flow-at-risk figure instead of a qualitative shrug.
A few practices separate useful scenario work from a spreadsheet exercise nobody trusts:
- Anchor assumptions in historical precedent where possible, citing the actual downturn or shock you’re modeling against.
- Test sensitivity on the two or three assumptions that drive most of the outcome variance, rather than treating every input as equally important.
- Validate assumptions with people who actually operate in the sector, not just desk research.
- Present a range, not a single point estimate, since false precision undermines credibility with the board.
Pro Tip: When presenting scenario outputs to senior stakeholders, lead with the dollar impact on earnings or cash flow, not the underlying assumptions. Executives remember “this could cost us $4 million in the adverse case” far longer than they remember the volume and pricing inputs that got you there.
Turning Risk Scores Into Board-Ready Recommendations
A heat map full of red dots is useless if it doesn’t translate into a decision. The gap between a well-built risk analysis and one that actually changes behavior is almost always in how the results get mapped to action.
Start by connecting each prioritized risk to a specific response tied to organizational risk appetite: avoid it, mitigate it, transfer it through insurance or hedging, or formally accept it. A risk in the red zone that gets “accepted” without documentation is a decision someone will have to explain later, so make that choice explicit and recorded, not implicit and forgotten.
Aggregation matters just as much at the reporting stage as it did in the analysis stage. Senior leadership doesn’t need forty individual risk scores; they need a portfolio view showing where concentration exists across business lines. If three product groups all carry high exposure to the same input cost risk, that’s a single strategic conversation, not three separate line items on a dashboard.
Frame response options in cost-benefit terms wherever you can. Hedging a commodity exposure has a real, quotable cost; leaving it unhedged has an estimated cost distribution. Putting both numbers next to each other is what actually moves a mitigation decision through committee.
- Track residual risk after each response, not just the original gross exposure.
- Use consistent dashboard metrics quarter over quarter so trends are visible, not just snapshots.
- Flag any risk moving categories (yellow to red) immediately rather than waiting for the next scheduled review.
A Compact Case Study: Applying the Framework to Regional Trucking
Consider a mid-size logistics company evaluating exposure in regional trucking, a sector facing simultaneous pressure from fuel volatility, driver shortages, and freight rate compression.
- Scope: The analysis covers dry van trucking within a defined regional market, using NAICS-level industry benchmarks for cost structure and margin trends.
- Identification: Interviews with dispatch and procurement teams, combined with trade publication data, surface four primary risks: fuel price volatility, driver labor cost inflation, freight rate cyclicality, and rising insurance premiums.
- Scoring: Fuel volatility scores high impact but moderate likelihood in the near term. Labor cost inflation scores high on both impact and likelihood, given persistent driver shortages. Freight rate cyclicality scores high impact and high likelihood, since the sector was already showing softening volumes.
- Scenario assumptions: The adverse case assumes freight rates fall 8%, fuel costs rise 10%, and driver wages climb 6%, compressing operating margin from a sector average near 8% down toward 3%.
- Heat map interpretation: Freight rate cyclicality and labor cost inflation land in the red zone together, flagging a correlated risk cluster rather than two independent line items.
- Recommended response: Lock in fuel hedges for a portion of projected volume, renegotiate customer contracts to include fuel surcharge clauses, and monitor driver turnover rates monthly as an early warning indicator for the labor cost risk.
The pattern generalizes: scope tightly, score honestly, watch for correlated clusters, and pick responses that address the cluster rather than each risk in isolation.
Where Most Industry Risk Analysis Efforts Go Wrong
The biggest mistake I see repeated across risk teams is applying one scoring model to every sector under review, as if a regulatory risk in pharmaceuticals behaves the same way as a regulatory risk in trucking. It doesn’t. A one-size-fits-all matrix might be efficient to build, but it flattens exactly the distinctions that make the analysis worth doing in the first place.
The second mistake is treating risks as independent line items when they aren’t. Correlated risks compound, and a heat map that scores each risk in isolation will systematically understate the tail scenario where two or three things go wrong together. That’s the scenario that actually sinks companies, not the single, well-flagged risk everyone saw coming.
If your data is thin, don’t wait for perfect inputs before acting. A rough sector benchmark applied consistently beats a precise company-specific number applied inconsistently. Start with published industry data, apply conservative assumptions where your own history is missing, and refine as better data becomes available.
Finally, build this into the planning calendar rather than running it as a one-off project. Industry conditions shift faster than most annual planning cycles account for, and a risk analysis that only gets revisited when something already went wrong is reactive by design, not strategic.
— Danny
Put Industry Benchmarks Behind Every Risk Score You Report
Bizminer is the direct route to the granular sector data this whole process depends on, without the guesswork of stitching together public filings and trade association estimates yourself. You get customizable industry reports built to your exact NAICS code and geography, the same underlying data that has held up under scrutiny in U.S. Tax Court and gets used by government agencies for their own analytical work.
Whether you’re running a quick sector screen for an underwriting decision or building a full earnings-at-risk model for board reporting, Bizminer’s market and industry research platform gives you the benchmark data to back it up. Business advisors and accounting professionals already use these reports to support client recommendations with defensible numbers rather than estimates. Start by pulling a custom industry report for the specific sector you’re evaluating, and build your next risk review on data that can survive a challenge.
Further Reading and Primary Sources
- Deloitte/COSO: Risk assessment in practice
- GARP: Stress-testing, a practical guide
- Bizminer: Why Bizminer
Sources
Reliable industry risk analysis runs on three categories of data: financial benchmarks (margins, turnover ratios, cost structures by sector), price and demand series (input costs, output pricing trends), and concentration metrics (customer, supplier, and geographic concentration within a sector). Regulatory filings, government statistical releases, and structured industry scoring services all contribute pieces of this picture, but few sources combine them at the granularity a working risk team actually needs.
This is the gap Bizminer’s customizable industry reports are built to close. The platform draws on public and private datasets across more than 9,000 distinct markets, segmented by industry, geography, and company size, giving analysts benchmark data specific enough to feed directly into an earnings-at-risk model rather than a generic sector overview. That specificity matters more than it sounds: a national average margin for “manufacturing” tells you almost nothing useful, while a regional benchmark for a six-digit NAICS code tells you where your exposure actually sits relative to peers.
Bizminer’s data carries a credibility marker worth noting for risk teams building defensible models: the underlying figures are accepted as evidence in U.S. Tax Court and used by government agencies for their own analytical work. That’s a meaningfully higher bar than most commercial data providers clear, since it means the methodology has survived scrutiny in an adversarial legal setting, not just a marketing claim.
A risk model is only as credible as the data feeding it. When your benchmarks have been accepted in tax court proceedings and used by government agencies, the underlying rigor has already been tested by people whose job is to find the holes in it.
Combining proprietary sector data with internal measures produces the strongest results. Internal loss history and claims data tell you what already happened to your organization specifically; external benchmarks tell you how exposed the sector is broadly, including risks your own history hasn’t captured yet because you haven’t experienced them yet. Relying on internal data alone is how risk teams get caught by a shock the rest of their sector saw coming.