A NAICS code is a six-digit U.S. industry classification that decides your SBA size standard, which federal contracts you can bid on, and how agencies and lenders benchmark your business against competitors. Federal agencies, the IRS, insurers, and contracting officers all read this one number as a shorthand for what your business actually does.
The immediate action matters more than the theory: check that the code on your last tax return matches your current primary activity, and confirm it against the Census NAICS search before you register on SAM.gov or bid on anything.
- A wrong code can bump you out of small-business set-asides you’d otherwise qualify for.
- Insurers and the IRS use your NAICS code to compare your numbers against industry norms.
- The fix is usually a five-minute lookup, not a legal headache.
Key Takeaways
Your NAICS code determines your SBA size standard, contracting eligibility, and how the IRS and insurers benchmark your business against industry peers.
| Point | Details |
|---|---|
| Six digits, five levels | Sector, subsector, industry group, NAICS industry, and national industry narrow your classification step by step. |
| Read the exclusions first | Most misclassification errors come from skipping the “includes/excludes” text on the code page. |
| The contracting officer’s code rules | On any solicitation, the officer’s assigned NAICS code sets the size standard, not your own listed code. |
| Update every system separately | Tax forms, SAM.gov, insurers, and state filings don’t sync automatically after a pivot. |
| Benchmark after you classify | A verified code unlocks accurate peer comparisons for lending, contracting, and valuation work. |
Table of Contents
- NAICS Codes Explained: Reading the Six Digits
- Why Your NAICS Code Affects Contracts, Taxes, and Loans
- How to Find Your NAICS Code in Four Steps
- Who Actually Assigns Your NAICS Code?
- What Goes Wrong When Your NAICS Code Is Off
- Updating Your NAICS Code Across Every System
- NAICS vs. SIC and Where to Verify Your Code
- Turning Your NAICS Code Into a Benchmarking Advantage
- Why the Code Itself Is the Easy Part
- Sources
NAICS Codes Explained: Reading the Six Digits
NAICS is a hierarchical system, and each digit narrows the classification further. Think of it like a zip code for your industry, moving from a broad region down to a specific block.
- Sector (2 digits): The broadest category, like 54 for Professional, Scientific, and Technical Services.
- Subsector (3 digits): Narrows the sector, such as 541 for Professional, Scientific, and Technical Services specifically.
- Industry Group (4 digits): Gets more specific, like 5415 for Computer Systems Design and Related Services.
- NAICS Industry (5 digits): This level, per the Economic Census guidance, is comparable across the U.S., Canada, and Mexico.
- National Industry (6 digits): The final digit adds U.S.-specific detail, landing you at something like 541511, Custom Computer Programming Services.
That sixth digit is where the Bureau of Labor Statistics notes NAICS diverges from its Canadian and Mexican counterparts, since it captures detail unique to how the U.S. economy is organized, particularly in services.
Why Your NAICS Code Affects Contracts, Taxes, and Loans
The code isn’t paperwork trivia. It’s the input that drives several decisions you actually care about.
- Federal statistics: The Census Bureau and BLS use NAICS to build the Economic Census and employment data you might rely on for market research.
- SBA size standards: Every NAICS code carries its own threshold for what counts as a “small business,” measured in either annual receipts or employee count.
- Contracting eligibility: The contracting officer assigns the NAICS code on a solicitation, and that single code determines the size standard for that specific opportunity.
- Tax and insurance benchmarking: The IRS and insurance auditors compare your reported numbers against industry peers under the same code.
Fast fact: SBA size standards vary widely by industry. Some codes cap eligibility at a set dollar amount in annual receipts, while others measure by employee headcount, so the same revenue figure can qualify you as small in one code and disqualify you in another.
How to Find Your NAICS Code in Four Steps
Finding the right code takes minutes if you search by what generates your revenue, not by the products you sell.
- Go to the Census NAICS search tool and search by keyword first, then confirm with the numeric code.
- Read the “includes” and “excludes” text on the six-digit code page. Most misclassifications happen here, not in the title.
- Pull your last tax return and SAM.gov profile to see what code you’re currently using.
- If two codes seem to fit, pick the one tied to your primary revenue activity, not a secondary service.
Pro Tip: If you genuinely can’t decide between two adjacent codes, call the Census Bureau’s NAICS help line or ask an accountant who works with your industry. A ten-minute call beats a contested audit or a bid protest later.
Who Actually Assigns Your NAICS Code?
You self-select your code in most everyday contexts, but agencies take that decision away from you in a few specific situations.
- You choose it on tax forms, loan applications, insurance paperwork, and your SAM.gov registration.
- The Census Bureau assigns it for Economic Census purposes based on your reported activities.
- The contracting officer assigns it on every solicitation, and per SBA size regulations, that code controls the size standard for that opportunity regardless of what you’ve listed elsewhere.
If you think a contracting officer picked the wrong code for a solicitation, there’s a narrow window to appeal that designation to the SBA before the deadline closes. Waiting past that window generally forfeits the challenge.
It’s also worth listing accurate secondary codes in your SAM.gov profile. Contracting officers and prime contractors search by NAICS code, and a well-chosen secondary code puts you in front of opportunities your primary code alone would miss.

What Goes Wrong When Your NAICS Code Is Off
The consequences scale with the context, and government contracting carries the sharpest teeth.
- IRS scrutiny: The IRS uses DIF scoring to flag returns where deductions or income look unusual for the stated industry. The wrong code can put you next to a peer group your numbers don’t resemble.
- Insurance audits: Insurers classify premiums by industry risk, and a mismatched code can trigger a retroactive premium adjustment after an audit.
- Contracting penalties: Deliberate misrepresentation of size status tied to a NAICS code can lead to suspension, debarment, or False Claims Act exposure, which carries real civil liability.
- The root cause is usually simple: picking a code based on your company name or a secondary product line instead of your primary revenue activity.
The fix is almost always preventive: read the “excludes” text on your code’s Census page before you commit to it, not after a solicitation officer or auditor questions it.
Updating Your NAICS Code Across Every System
A code change rarely happens in one place. Business pivots mean updating several forms that don’t automatically sync with each other.
- Enter the new code on your next filing, whether that’s Schedule C, Form 1065, or Form 1120-S.
- Update your SAM.gov registration directly, since federal systems don’t pull from your tax return.
- Notify your insurer and any lenders who based terms on your prior classification.
- Check your state’s business filing requirements. Only a minority of states ask for a NAICS code on formation documents, but a few do.
Time the update around your SAM.gov renewal cycle, right after a material pivot in what your business does, or before you submit a bid where the code will be scrutinized.
NAICS vs. SIC and Where to Verify Your Code
NAICS replaced the older Standard Industrial Classification system in 1997, and the difference matters if you’re comparing old data or dealing with a legacy database still using SIC. NAICS recognizes far more service industries than SIC ever did, which is why BLS still maintains concordance guidance between the two systems. You’ll still see SIC codes surface in old Dun & Bradstreet-style records or older state filings, but every current federal use runs on NAICS, revised on a set schedule with the next major update planned for 2027.
For verification, four sources cover nearly every scenario you’ll run into:
- The Census NAICS search for official code definitions and cross-vintage concordances.
- BLS for interpretive guidance on how the structure applies to labor statistics.
- SAM.gov to check what code appears on your registration and on active solicitations.
- The SBA size standards table to check your receipts or employee threshold against your assigned code.
Turning Your NAICS Code Into a Benchmarking Advantage
Once you know your code, the real work starts: figuring out how your numbers compare to your peers. Bizminer’s NAICS Industry Search Tool lets you pull financial profiles across more than 9,000 markets segmented by industry, geography, and company size, all tied directly to NAICS classifications.
Bizminer’s data has been accepted in U.S. Tax Court and is used by government agencies, which matters if you’re building a case for a valuation, a loan application, or a contracting capability statement.
- Prepare lending packages with industry-specific financial benchmarks a loan officer will recognize.
- Build peer comparisons for a client’s Schedule C review or SBA loan application.
- Pull an industry description tied to your exact code for a federal capability statement.
If your business falls under administrative support or waste management, or you need a quick reference for how NAICS sectors map to Bizminer’s coverage, those pages show what a granular industry profile actually looks like.
Why the Code Itself Is the Easy Part
Most of the advice out there treats finding your NAICS code as the finish line. It isn’t. The lookup takes five minutes on the Census site. The part people skip is reading the “excludes” language on the six-digit page, and that’s exactly where audits, bid protests, and insurance disputes start.
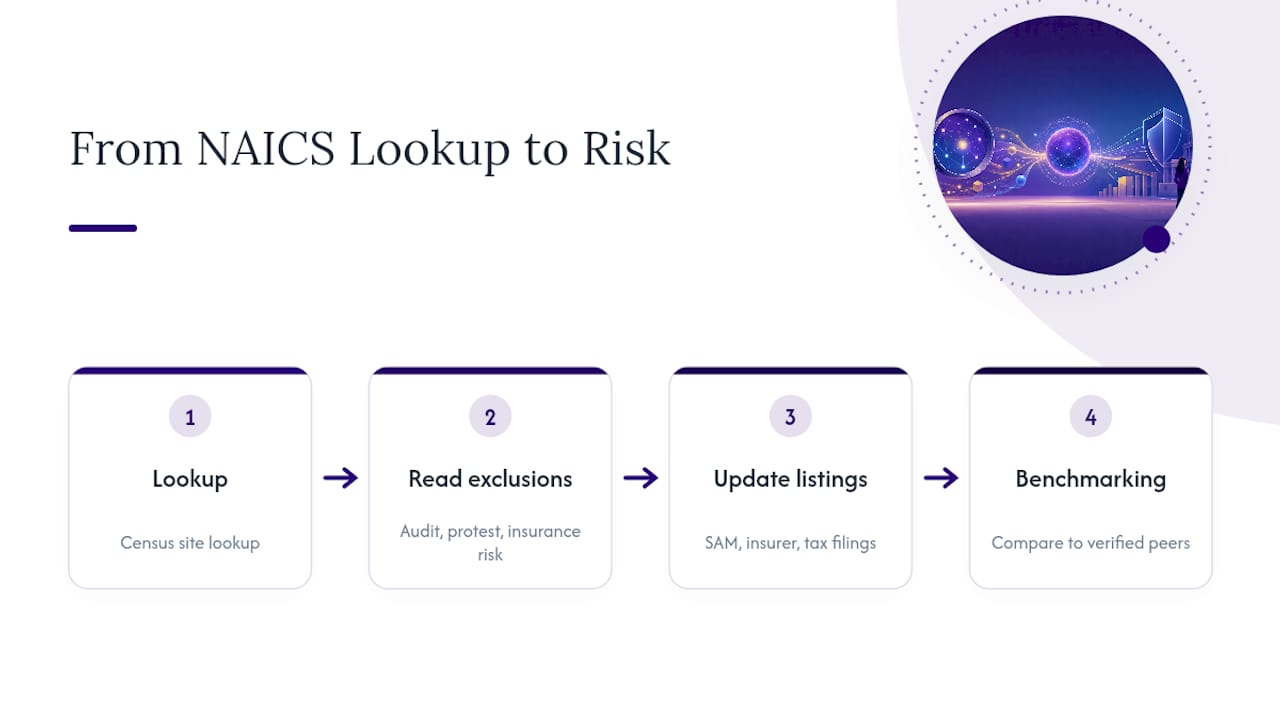
The conventional advice also underweights how often businesses need to revisit their code. A company that pivots from retail to e-commerce, or from general contracting to specialty subcontracting, rarely goes back to update SAM.gov, their insurer, and their next tax filing all at once. Each system asks separately, and nothing forces you to sync them.
If you’re a small-business owner or advisor doing this for a client, prioritize two things before anything else: confirm the primary revenue activity matches the code exactly, and check that code against every place it’s currently listed, not just the most recent one you touched. Everything downstream, from set-aside eligibility to your audit risk profile, traces back to whether that first match was accurate.
Once the code is locked in, benchmarking your numbers against verified industry peers is where the real strategic value starts. That’s the step most owners never get to because they treat the code as paperwork instead of as the key that unlocks comparison data.
— Danny
Sources
- North American Industry Classification System (NAICS) at BLS
- 13 CFR Part 121 – Small Business Size Regulations (CFR)