For U.S. professionals, Tax Court valuation data means primary Tax Court opinions plus IRS guidance, including Publication 561 and the Internal Revenue Manual, combined with defensible market benchmarks. Those three elements, used together, are what persuades the Court. Bizminer’s market data has been accepted in Tax Court proceedings, and pairing it with the right opinions and IRS standards gives a valuation position the documentation it needs to survive examination and litigation.
TL;DR:
- Tax Court opinions, IRS guidance, and current market benchmarks must be combined and thoroughly documented to support a valuation that can withstand examination and litigation.
- Recurring dispute patterns include valuation discounts linked to entity restrictions, the legitimacy of tax-affecting S earnings, and the timing and control issues in family limited partnerships.
- A defensible report requires transparent data sources, detailed reconciliation of approaches, and direct ties of discounts to specific facts about the entity, not generic datasets.
- Relying solely on older case law or outdated market data risks mismatching current conditions; balancing legal reasoning with fresh, granular data is essential.
- Bizminer provides accepted, transparent market data supporting fact-specific comparables, which can strengthen valuation reports and court exhibits.
Table of Contents
- Where to find and what counts as authoritative Tax Court valuation data
- Key Tax Court case patterns and precedents that affect valuation outcomes
- Accepted valuation approaches, IRS rules, and what makes an expert report persuasive
- Practical workflow for building a defensible valuation or filing
- How Bizminer’s court-accepted data supports Tax Court-ready valuation analysis
- Updates on recent significant Tax Court valuation rulings
- Extracting and analyzing quantitative data from Tax Court opinions
- Applying Tax Court valuation data to reports and litigation strategy
- Limitations of relying solely on Tax Court data
- Best practices for using Tax Court valuation data
- How to get started with Bizminer for valuation and court-prepared exhibits
- Sources
- FAQ
Where to find and what counts as authoritative Tax Court valuation data
The United States Tax Court publishes its opinions directly, and these opinions are the backbone of any serious valuation analysis. Full Tax Court opinions, memorandum opinions, and summary opinions are posted on the court’s own site, and the court also compiles monthly pamphlet volumes that bind opinions together for reference. Slip opinions appear first, often within days of a ruling, and the bound reports follow later with final pagination for citation.
IRS guidance fills the gap between what the court decided and what an examiner expects to see before a case ever reaches litigation. IRS Publication 561 lays out the fair market value standard for transfer tax purposes, grounded in the willing buyer and willing seller test codified at 26 CFR §25.2512-1. IRM 4.48.4 gives examiners a working framework for evaluating appraisals submitted with estate, gift, and generation-skipping transfer returns.
Reading an opinion for its data means pulling out specific, repeatable elements rather than treating the case as background reading. When you review a case, extract:
- The valuation date and why the court accepted or rejected the appraiser’s chosen date.
- The facts the court found material, including entity restrictions, pending transactions, and buy-sell agreements.
- How the court treated competing expert testimony and which methodology it favored.
- The discount rates or percentages applied for lack of control or marketability, and the reasoning behind them.
- Any language the court used that signals a broader standard, since these phrases often get cited in later cases.
Monitoring for updates matters as much as the initial research. New opinions post on a rolling basis, and a case decided last month can shift how examiners view a particular industry or entity structure. Professionals who track filings regularly catch these shifts before a client’s return is selected for audit rather than after.
Key Tax Court case patterns and precedents that affect valuation outcomes
Tax Court valuation disputes tend to cluster around a small number of recurring issues, and recognizing the pattern before you open a case saves time. Three fact patterns dominate: minority and marketability discounts on closely held interests, tax-affecting of S corporation earnings, and family limited partnership structures created shortly before a transfer.
- Discounts for lack of control and lack of marketability remain the most litigated issue in closely held business valuation, and the Court has consistently rejected mechanical application of a single published discount study in favor of case-specific evidence tied to the entity’s actual restrictions and transfer history.
- S corporation tax-affecting continues to divide practitioners and examiners. Guidance in the S Corporation valuation job aid indicates that tax-affecting earnings requires compelling evidence that a hypothetical buyer and seller would actually negotiate for an entity-level tax adjustment, not simply a generic assumption that S status has value.
- Family limited partnership cases turn heavily on formation timing and management substance. When an entity was created shortly before a gift or death, and the transferor retained effective control over distributions or asset use, the Court has looked past the partnership form to the underlying economic reality.
Fact patterns beyond the core methodology often decide these cases. Disclosure completeness on the gift tax return matters enormously: a Form 709 that fails to describe the valuation method and the financial data behind it can leave the statute of limitations open indefinitely under IRC §6501©(9). An appraisal that relies on stale financials, or one that ignores a merger or sale that was reasonably foreseeable as of the valuation date, tends to draw the harshest judicial scrutiny. IRS guidance on foreseeability shows that examiners and courts will weigh pending transactions that a hypothetical willing buyer would have known about, even when the deal closed after the valuation date.
The throughline across these patterns is that the Court treats valuation as a factual inquiry, not a formula to apply mechanically. Case summaries describing decisions such as Mandelbaum and Litchfield show a consistent preference for weighing all credible evidence over defaulting to a single discount study or a fixed percentage. A report built around one number from one source rarely survives cross-examination, while a report that shows its work across multiple data points tends to hold up.
Accepted valuation approaches, IRS rules, and what makes an expert report persuasive
The IRS recognizes three general approaches for valuing a closely held business or fractional interest: asset-based, market, and income. IRM 4.48.4 directs examiners to expect appraisers to consider all three and to justify any departure from the approach that best fits the entity’s facts. An asset-based approach fits a holding company or real estate entity where underlying asset values drive worth. A market approach fits businesses with identifiable comparable transactions or public guideline companies. An income approach fits operating businesses where future cash flow, not asset value, is what a buyer would actually pay for.
Examiner expectations extend beyond picking the right approach. When a report’s conclusions look inconsistent with internal IRS benchmarks, examiners can refer the matter to specialists through the Specialist Referral System, drawing on Engineering, Art Appraisal Services, or Outside Fee Appraisals under IRM 4.25.12. A report that anticipates this scrutiny and documents its reasoning up front is far less likely to trigger a costly referral.
A persuasive report includes:
- A clear statement of the data sources used, including which years and which comparable sets.
- A reconciliation section explaining how the analyst weighted each approach to reach the final conclusion.
- A specific, sourced justification for every discount applied, rather than a flat industry-standard percentage.
- Disclosure of 100% of the entity value before any discounts, which is required for adequate disclosure under Treasury Regulation §301.6501©-1(f)(2)(iv).
The most common weakness in reports that fail under examination or in court is a discount pulled from a published study without connecting it to the entity’s specific restrictions, buy-sell terms, or transfer history. The fix is straightforward: tie every number to a fact about the entity being valued, not to an average from a dataset the subject company never appears in.
Pro Tip: Build your discount support around the entity’s own governing documents first, and use published studies only to confirm the range, not to set the number.
Practical workflow for building a defensible valuation or filing
A defensible valuation report follows a sequence, and skipping steps is what creates exposure later. The workflow below reflects how experienced preparers move from research to a filed return that can survive audit.
- Identify Tax Court opinions that match your entity type, industry, and valuation date, and triage them by how closely the facts align with your client’s situation.
- Pull market evidence and industry benchmarks to populate your comparables, using granular data on revenue multiples, margins, and sample sizes rather than generic industry averages.
- Draft the expert report with full disclosure of 100% entity value, a documented discount breakdown, and supporting schedules that show the math behind every adjustment.
- Prepare for cross-examination by keeping backup data, running sensitivity analyses on your key assumptions, and retaining records long enough to avoid falling into the open-ended exposure created by inadequate disclosure under IRC §6501©(9).
A Form 709 that omits the valuation method or financial data behind a reported gift value can leave the statute of limitations open indefinitely, according to IRS guidance on disclosure adequacy. That single procedural failure can undo years of otherwise sound valuation work, which is why the disclosure checklist deserves the same attention as the valuation conclusion itself.
Sensitivity analysis deserves particular attention in the cross-examination prep step. A report that shows how the conclusion moves under a range of discount rates, growth assumptions, or comparable sets demonstrates that the analyst tested the number rather than backed into it. Courts and opposing experts both look for that kind of transparency, and its absence is one of the fastest ways to lose credibility on the stand.
How Bizminer’s court-accepted data supports Tax Court-ready valuation analysis
Market data accepted by tax and government entities can be used to assemble exhibits that withstand both examiner review and cross-examination. The platform covers more than 9,000 unique markets segmented by industry, geography, and company size, which lets an analyst build a comparables appendix that reflects the subject entity’s actual competitive set instead of a broad national average.
- Reports can be filtered to niche NAICS segments, specific geographies, and company size bands, which supports the fact-specific analysis the Court expects.
- Sample sizes and source lists are documented within each report, giving examiners and opposing counsel a transparent basis to evaluate the data behind a discount or multiple.
- Financial Report, Market Report, and Valuation Report products can populate sensitivity tables that show how a conclusion holds up across a range of comparable sets.
| Report type | What it supports in a valuation file |
|---|---|
| Valuation Report | Direct comparables and multiples for the subject entity’s market segment |
| Industry Financial Performance | Benchmark ratios to test the reasonableness of income approach assumptions |
| Company Profile | Entity-level financial context for competitor or comparable company analysis |
| Market Report | Market-level trend data to support growth and discount rate assumptions |
Analysts preparing exhibits for industry financial benchmarks or building valuation multiples by industry into a report can draw on this same granularity to document exactly which data points fed the final number, satisfying the disclosure expectations examiners and the Court both look for.
Updates on recent significant Tax Court valuation rulings
Valuation standards in Tax Court do not move in dramatic swings so much as steady refinement of how existing doctrine applies to new fact patterns. Recent IRS guidance on foreseeable post-valuation-date events, including memoranda addressing pending mergers, reflects a continuing willingness to look at what a hypothetical buyer would have known at the time, even when the triggering event closed afterward. That approach keeps pressure on appraisers to research pending transactions thoroughly rather than treating the valuation date as a hard cutoff for available information.
The tax-affecting debate for S corporations remains active in IRS valuation guidance, with the S Corporation valuation job aid continuing to shape how examiners approach these interests. Analysts should treat this as an area where the underlying reasoning, not a fixed rule, drives outcomes.
Academic analysis of the repeal of the General Utilities doctrine has also kept attention on how built-in capital gains liabilities get reflected in valuation models, particularly the timing and present value of any expected future tax cost. Professionals tracking these threads should read new opinions as they post rather than relying on a single older case as the final word, since the fact-specific nature of this area means each new ruling can shift how a particular argument is received.
Extracting and analyzing quantitative data from Tax Court opinions
Turning a stack of opinions into usable data means building a structured extraction process rather than reading cases one at a time and hoping the patterns stick. Start by creating a simple log for every case reviewed, capturing the entity type, industry, valuation date, discount percentages applied, and which approach the court favored.
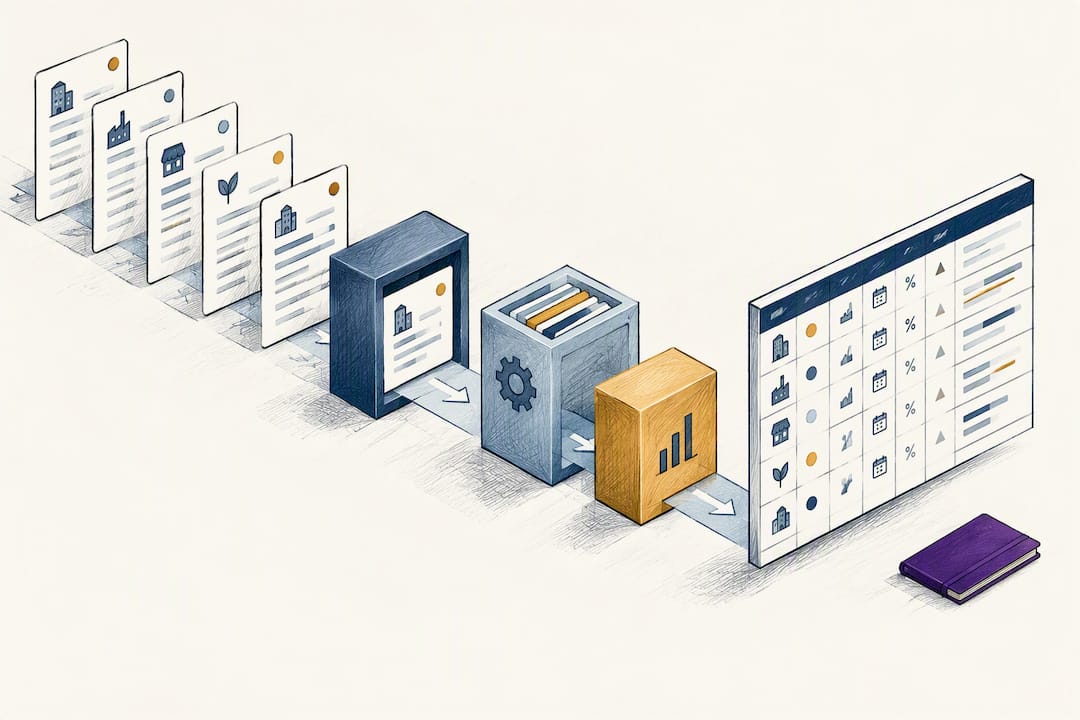
Once several comparable cases are logged, trend analysis becomes possible. Plotting discount percentages by entity type or by year can reveal whether courts in a particular fact pattern, such as minority interests in real estate holding companies, are trending toward a narrower or wider range than older cases suggest. This kind of comparable-case compilation also helps identify outlier rulings that might not represent the mainstream view and should be cited cautiously.
The most useful extraction captures not just the final number but the reasoning path: which expert’s approach the court found more credible, what specific facts drove that preference, and whether the court criticized any part of the methodology even while accepting the conclusion. That reasoning is often more valuable to a new report than the discount percentage itself, since it tells you what to document, not just what number to reach.
Applying Tax Court valuation data to reports and litigation strategy
A practical application starts before litigation ever begins. When drafting an expert report for a gift tax return, an analyst can cite comparable Tax Court holdings to justify a chosen discount range, showing the client’s return reflects the same reasoning the Court has already accepted in similar fact patterns rather than an aggressive outlier position.
In an active dispute, opinions serve a different function: identifying weaknesses in the opposing expert’s approach before deposition or trial. If a comparable case shows the Court rejecting a discount study because it lacked entity-specific adjustment, and the opposing report makes the same unadjusted assumption, that gap becomes a direct line of cross-examination.
Litigation strategy also benefits from matching valuation dates and industries as closely as possible. A case involving a minority interest in a manufacturing company decided under a very different set of facts, such as a pending sale the taxpayer failed to disclose, carries less persuasive weight for a stable family retail business with no transaction on the horizon. Matching fact patterns carefully, rather than citing the first case with a favorable number, is what makes the citation credible to the Court rather than an example of cherry-picking a result.
Limitations of relying solely on Tax Court data
Tax Court opinions describe what happened in a specific dispute, and that is both their strength and their limit. A discount percentage the Court accepted in one case reflects that entity’s restrictions, that industry’s conditions at that time, and that particular set of experts. Treating it as a universal benchmark for a different entity, industry, or valuation date risks the same mechanical-formula criticism the Court has leveled at appraisers who lean too hard on published discount studies.
Opinions also lag current market conditions by the time a case works through the litigation process, often years after the original valuation date. An analyst valuing an entity today needs current industry benchmarks and market data alongside the legal reasoning from older cases, not a substitute for it. Case law tells you how courts reason and what evidence persuades them, while current financial data tells you what a comparable business actually looks like today.
The safest approach uses Tax Court opinions to understand the standard of proof and the kinds of evidence that hold up, then layers in current, granular market data to build the specific numbers a report needs. Relying on either source alone leaves a gap the other side’s expert will find.
Best practices for using Tax Court valuation data
In practice, the reports that hold up share one habit: every number traces back to a named source, and every discount ties to a fact about the entity, not an average pulled from an unrelated dataset. Professionals who document that chain from the start spend far less time defending their work later, because there is nothing left to reconstruct under pressure. My rule of thumb is simple: if you cannot show the reasoning behind a number in one sentence, you have not finished the analysis. Cite primary sources, including the specific opinion or IRM section behind each position, and make sure the report identifies the credentials and methodology of the professional who prepared it.
— Danny
How to get started with Bizminer for valuation and court-prepared exhibits
Building a defensible valuation exhibit does not require assembling data from a dozen scattered sources. Valuation Report, Industry Financial Performance report, and Company Profile products provide documented sample sizes and source lists, and a customizable API feed lets practices pull granular data into existing report templates.
For a one-off engagement, a Financial Report or Valuation Report can populate the comparables and benchmarks section of a single client file. For a practice that handles recurring gift and estate work, the Bizminer subscription gives ongoing access across the platform’s 9,000-plus market segments. Visit Bizminer’s pricing page to review report options and request the data extract your next filing or exhibit needs.
Sources
- IRS Publication 561, Determining the Value of Donated Property
- 26 CFR § 25.2512-1 – Valuation of property; in general
FAQ
What counts as US Tax Court valuation data?
It refers to the combination of published Tax Court opinions, IRS guidance such as Publication 561 and the IRM valuation sections, and current market benchmarks. Professionals use these together to support a valuation position rather than relying on any single source.
How does the Tax Court decide which valuation approach applies?
The Court does not favor a fixed formula, and instead weighs asset, market, and income approaches based on the entity’s specific facts, consistent with IRM guidance directing examiners to expect a justified choice of method. Case summaries describing decisions like Mandelbaum show the Court rejecting rigid discount studies in favor of case-specific evidence.
Why does Form 709 disclosure matter for the statute of limitations?
A Form 709 that fails to adequately describe the valuation method and financial data used can trigger the §6501©(9) exception, which allows the IRS to assess additional tax at any time rather than within the standard limitations period. Adequate disclosure includes 100% of entity value before discounts and a clear breakdown of each discount applied.
Does the IRS require tax-affecting for S corporation valuations?
No single rule mandates tax-affecting, and the S Corporation valuation job aid indicates it requires compelling evidence that a hypothetical buyer and seller would negotiate for an entity-level tax adjustment. Absent that evidence, examiners and courts have generally been skeptical of applying a corporate-style tax adjustment to pass-through earnings.
Can Bizminer data be used as market evidence in a Tax Court valuation report?
Bizminer market data has been accepted in U.S. Tax Court and is used by government agencies, and its reports document sample sizes and sources across thousands of industry segments. That transparency supports the fact-specific comparables and benchmarks a valuation report needs to withstand examiner and judicial scrutiny.