Private company valuation data is the set of financial benchmarks, comparable-company figures, market multiples and risk inputs you use to put a defensible number on a business with no stock price. For most U.S. small and mid-size businesses, that means industry financial ratios, transaction-based multiples, and size and marketability adjustments, all documented well enough that a reviewer can retrace your steps. This guide covers what to collect, where it comes from, and how to avoid the mistakes that make a valuation fall apart under scrutiny.
TL;DR
- A private company has no observable share price, so valuation depends on outside data: industry benchmarks, comparable multiples, and adjustments for liquidity and control.
- The three core approaches are income (discounted cash flow), market (multiples of similar firms) and asset-based. Good data supports all three and lets you cross-check them.
- For tax work, the IRS expects a documented assignment, valuation date, purpose and standard of value. A single mechanical output is not enough.
- No single source covers every industry, size band and region. Combine sources and record each one.
- Match the data to the company: size, niche, geography and intangible value change how reliable a multiple is.
Table of Contents
- Why private company data is harder than public data
- The three approaches and the data each one needs
- Industry benchmarks: the base layer
- Valuation multiples: use them, but know their limits
- Adjustments that private data never includes
- What the IRS expects from your data
- Why one data source is never enough
- When the company is venture-backed
- A step-by-step workflow for building a defensible value
- Our perspective
- Get benchmark and valuation data for your engagement
- FAQ
- Sources
Why private company data is harder than public data
With a listed company, the market gives you a price every second and audited statements every quarter. A private company gives you neither. The CFA Institute’s private company valuation reading frames it this way: the process is conceptually the same as for public firms, but you must adjust for liquidity and control, and you must build risk-adjusted models yourself instead of leaning on a ticker.
That shifts the work. Instead of pulling a price, you assemble evidence:
- Subject company financials: income statements, balance sheets, owner compensation, and any non-recurring items you need to normalize.
- Industry financial benchmarks: margins, growth, leverage and turnover for companies like this one.
- Market evidence: multiples from comparable public companies or from private transactions.
- Discount and premium inputs: company-specific risk, size premia, lack of marketability and control.
- Economic and sector context: the outlook that explains why the numbers are what they are.
Each layer has its own data problem. Together they decide whether your conclusion is something a client, a lender or a court can rely on.
The three approaches and the data each one needs
The CFA Institute material groups private valuation into income, market and asset-based approaches. Here is what each one asks of your data.
| Approach | What it estimates | Data you need | Common weak spot |
|---|---|---|---|
| Income (DCF or capitalized earnings) | Present value of future cash flow | Normalized financials, growth outlook, discount rate inputs, industry margins | Projections with no outside benchmark behind them |
| Market (multiples) | Value implied by similar companies or deals | Comparable multiples by industry, size and period | Comparables that are too big, too different or too old |
| Asset-based | Value of net assets, often at fair value | Balance sheet, appraisals, intangible asset estimates | Missing intangibles such as software or trademarks |
No approach is automatically best. Practitioners writing in the Financial Analysts Journal note that asset-based multiples such as market-to-book can produce more precise, less biased estimates than earnings multiples. They also caution that any multiple’s reliability depends on company size and how much of the value is intangible. The practical lesson: the right approach depends on the company, and you should be able to say why you chose it.
Industry benchmarks: the base layer
Before you pick a multiple, you need to know whether the subject company is normal for its industry. Is its gross margin high or low? Does it carry more debt than peers? Does it collect receivables slower? Industry financial benchmarks answer those questions, and they feed every approach above.
Benchmarks do three jobs in a valuation:
- Normalizing: comparing the company’s ratios to peers shows which expenses or margins need adjusting.
- Supporting projections: a forecast that sits inside an industry range is far easier to defend than one with no reference point.
- Choosing risk inputs: a company weaker than its peers on leverage or profitability usually warrants a different risk assessment.
Our practical playbook on industry financial benchmarks walks through how to use them, and the financial ratios glossary defines each ratio so your report and your source agree on terms.
The filters matter as much as the numbers. A benchmark for an entire sector can hide the fact that a regional, 12-person firm behaves nothing like a national chain. Our guide to industry comps data and five filters that hold up in court covers narrowing by industry code, geography and size so the comparison set actually resembles the subject.
Valuation multiples: use them, but know their limits
Multiples are the fastest way to a market-based value, and the easiest to misuse. A revenue or earnings multiple is only meaningful when the comparison set matches the company on size, growth and risk. The same Financial Analysts Journal discussion warns that reliability varies with size and intangible share, and that forecasted earnings are a better base than trailing figures.
A few habits that keep multiples honest:
- Know what the multiple is built on. Earnings before what? Revenue from which period? Check the definitions before you compare. The definitions and limitations of Bizminer valuation multiples show what we mean by each one.
- Use a range, not a point. Report the spread and explain where the subject falls in it.
- Cross-check with a second approach. If a multiple says one thing and your DCF says another, the gap is information.
- Date your data. A multiple from a different market cycle is a different measurement.
For a sector-by-sector view, see our 2026 reference guide to valuation multiples by industry. If you already have a Bizminer report open and need to find the multiples inside it, the support article on locating valuation multiples takes you straight there.
Adjustments that private data never includes
Public-company multiples describe liquid shares that anyone can sell today. A private company is different, and the data does not adjust itself.
Lack of marketability. Private interests are harder to sell. Analysts frequently apply a discount for lack of marketability (DLOM), and the CFA Institute reading lists it alongside control premiums as a standard adjustment.
Control versus minority. A buyer of a controlling interest can change management, payouts and strategy. A minority holder cannot. Whether you apply a premium or discount depends on the interest being valued.
Size and company-specific risk. Small companies carry risks that large ones do not: customer concentration, key-person dependence, thinner capital. Size premia and specific-risk adders are ordinary inputs, but each should be supported by something you can cite.
Intangibles. Software, trademarks and customer relationships can drive most of a private company’s value and still be missing from the balance sheet. A CFA Institute Enterprising Investor article on five methods for intangible valuation explains why accounting standards make this gap hard to close. Methods such as relief from royalty exist for exactly this case.
What the IRS expects from your data
If the valuation is for estate, gift or other tax purposes, the standard is concrete. The Internal Revenue Manual’s business valuation guidelines call for defining the valuation issue, planning, identifying relevant factors, documenting specific information and analyzing it, with every relevant activity documented. A defensible tax appraisal starts by stating the assignment, the property, the valuation date, the purpose and the standard of value.
Rev. Rul. 59-60 is the long-standing framework for closely held stock, and it is not a formula. Appraisers weigh factors such as the economic outlook, industry condition and earning capacity. Courts look for documented, reasonable analysis, not a mechanical calculation. In practice, that means every input in your model should trace to a named source and date.
S corporations and tax affecting
S corporations are generally not subject to entity-level federal tax. When valuing their interests, an IRS valuation job aid, Income Tax Affecting for S Corp Valuation Purposes, addresses whether to reduce projected cash flows by a hypothetical entity-level tax. Our research reading of the IRS guidance is that you should not make that reduction unless you can show unrelated parties dealing at arm’s length would do so. Court decisions such as Gross v. Commissioner reinforce this line. If you are advising an S corporation owner, read the job aid itself, and bring in a credentialed appraiser for anything contested.
Owner pay also distorts the numbers, since it changes normalized earnings. A CPA firm’s small business guide to owner compensation is a helpful backdrop when you need to explain why reported profit and economic profit differ in a closely held company.
Why one data source is never enough
Private company data is fragmented. Some sources are strong on small-business sale transactions, some on venture rounds, some on financial statement ratios, some on company-level profiles. Each has a coverage gap, a time lag or a sampling bias. Our piece on why one private company data source isn’t enough explains how to combine them. The working rule is simple: for every number in the report, know where it came from, how many observations stand behind it and what it leaves out.
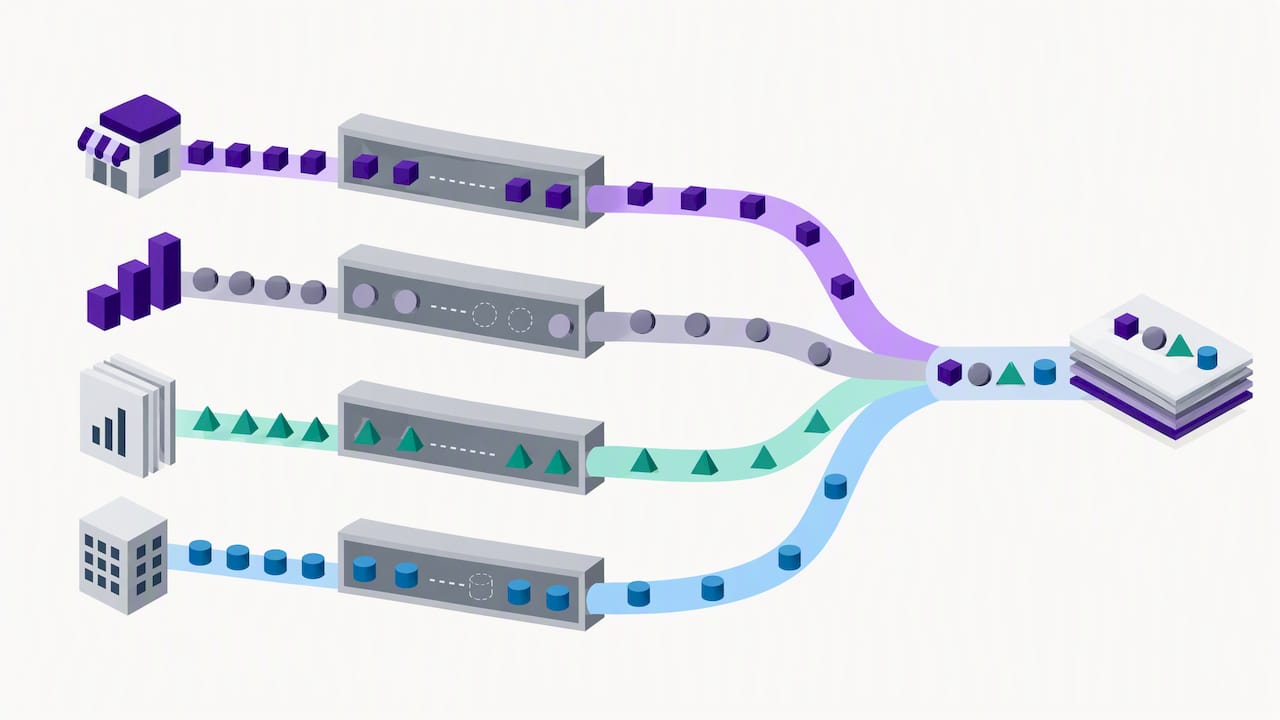
That discipline matters most when the audience is skeptical. For a reviewer, the question is rarely “is this number plausible?” It is “can you show me where this came from?” Our overview of audit-ready, court-accepted business valuation data sources lays out how valuers document that chain.
When the company is venture-backed
Everything above assumes an operating business with earnings. Venture-backed companies play by different rules. The 2026 NVCA Yearbook reports that $320 billion was deployed in 2025, with 65.4% of deal value going to AI. It also reports $217.1 billion in venture-backed exit value across 1,463 exits, more than double the prior year.
Two points from the same yearbook change how you read private-round data:
- Non-traditional investors, including hedge funds, sovereign wealth funds and corporate strategics, took part in 30% of 2025 deals but accounted for 83% of investment dollars. Valuations driven by that capital can detach from traditional venture metrics.
- Round labels like Series A say less than they used to, since very large deals now happen at seed stage. Look at the actual terms and the quality of the investors, not the label.
For a startup owner weighing equity against debt, a guide to startup funding options puts these valuation dynamics in the context of financing choices. For most Main Street companies, though, benchmarks and transaction multiples remain the working data.
A step-by-step workflow for building a defensible value
- Define the assignment. Write down the interest being valued, the valuation date, the purpose and the standard of value, as the IRS guidelines expect.
- Normalize the financials. Adjust for owner pay, one-time items and non-operating assets.
- Benchmark against peers. Pull industry ratios filtered by industry code, geography and size. Note where the company is better or worse than peers.
- Choose approaches and say why. Use at least two where the data allows.
- Select multiples with care. Match size, growth and period. Keep definitions consistent.
- Apply adjustments with support. Marketability, control, size and specific risk each need a documented basis.
- Reconcile and conclude. Explain how you weighted each method. Do not average blindly.
- Archive your sources. Record the source, date and sample behind every input.
Our perspective
We built Bizminer around one observation: the people who value private companies, accountants, advisors, lenders and academics, are rarely short of methods. They are short of data that fits the company in front of them and that they can defend afterward.
That is why we focus on granularity. Our platform covers over 9,000 unique markets, segmented by industry, geography and company size, so you can compare a regional specialist to similar firms instead of a whole sector. Our reports carry larger sample sizes and detailed source lists, and our data has been accepted in U.S. Tax Court and used by government agencies. We say that plainly because it is the standard the work is held to, not because it replaces your judgment.
Our advice is to treat data as evidence, not decoration. Write down the filter you used, the sample behind it and the date. If you cannot explain why a benchmark is the right one, a better one probably exists. And if two sources disagree, report the disagreement instead of hiding it. That honesty is what makes a valuation survive a review.
— Danny
Get benchmark and valuation data for your engagement
If you need company or industry figures for a valuation, we sell them by the report. An Industry Financial Performance report is 249 USD per report, and a Valuation Report is 349 USD per report, as published on our pricing page. Subscriptions and customizable API feeds are also available, and you can build a report around your own filters with our granular custom reports. Our market data API suits firms that want the same data inside their own workflow.
If you want to see what a valuation report contains before you buy, the support article on Bizminer’s business valuation report describes it. Teams doing deal work can also read how to test growth claims with market data for due diligence.
FAQ
How do you tell how much a private company is worth?
You estimate it with one or more of three approaches: income, market and asset-based. Then you adjust for marketability and control and document every input. Industry benchmarks and comparable multiples supply the outside evidence, and a defensible report explains why each was chosen.
What are the five methods of valuation?
There is no single official list of five. Most frameworks reduce to the income approach, the market approach and the asset-based approach, with variants such as capitalized earnings, comparable transactions and relief from royalty for intangibles. The CFA Institute reading organizes private valuation around the three core approaches.
Is there free private company valuation data?
Some public sources give partial context, such as filings, regulator guidance and industry yearbooks. Free sources rarely give you filtered benchmarks by niche, size and geography with a documented sample. If the valuation will be reviewed by a client, lender or the IRS, plan to use sources that list their methodology and inputs.
Does the IRS accept any valuation method?
The IRS does not prescribe one formula. Its guidelines require a documented assignment, valuation date, purpose and standard of value, and Rev. Rul. 59-60 calls for weighing all relevant factors. For tax disputes, work with a qualified business appraiser and an attorney or CPA familiar with the case.
Sources
- Private Company Valuation, CFA Institute
- 4.48.4 Business Valuation Guidelines, Internal Revenue Service
- Income Tax Affecting for S Corp Valuation Purposes, IRS
- Multiples Used to Estimate Corporate Value, Financial Analysts Journal
- The Intangible Valuation Renaissance: Five Methods, CFA Institute
- 2026 NVCA Yearbook
- NVCA 2026 Yearbook (PDF)